Quick Answer
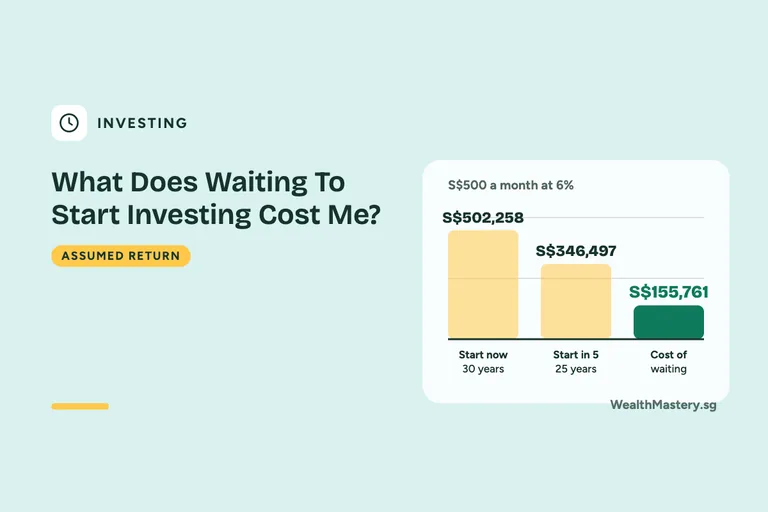
Starting later loses the longest-growing years, not just the payments you skip. S$500 a month at 6% for 30 years could grow to about S$502,258. Starting 5 years later could leave about S$155,761 less, although you would put in only S$30,000 less.
The Useful Number: S$500 a month at 6% for 30 years could grow to about S$502,258. Starting 5 years later could leave you with about S$155,761 less, though you would put in only S$30,000 less.
Why Does Starting Later Cost So Much?
Money invested early has the most years to earn returns, and then returns on those returns. When you delay, you lose the payments you skip and, more importantly, the longest-growing years of growth.
What Does A 5-Year Delay Cost Over 30 Years?
- Start now: S$500 a month for 30 years at 6%: About S$502,258
- Start in 5 years: S$500 a month for 25 years: About S$346,497
- Cost of waiting: About S$155,761
- Money you did not put in: S$30,000
- Monthly amount to catch up: About S$725
The return is an assumption, not a forecast. At a lower return the gap shrinks; at 0% it is just the S$30,000 you did not put in.
- Start Now: About S$502,258
- Start In 5 Years: About S$346,497
- Cost Of Waiting: About S$155,761
- Money Not Put In: S$30,000
Data as of . Source: MoneySense — Investment Risk.
What Does The Estimate Leave Out?
It assumes a steady return, payments at the end of each month and no fees, tax or inflation. Real markets go up and down, and investing comes with risk of loss.
What Comes Before Investing?
Keep an emergency fund and pay off expensive debt first: see the emergency fund guide. Then model your own plan with the compound growth calculator. This guide does not recommend any product.
Quick Check
Three statements from this guide. Tap True or False to check what you have read. Nothing is saved.
Card 1 Of 3
Starting 5 years later costs only the S$30,000 you did not put in.
Why?
The years you skip are the ones with the longest time to grow.
Card 2 Of 3
At a 0% return, the cost of waiting is just the payments you skipped.
Card 3 Of 3
You should invest before building an emergency fund.
Your Score
Try It With Your Numbers
Open the calculator with this guide’s example filled in. Then change the numbers to match your situation.
Open Cost Of Waiting Calculator →Frequently Asked Questions
Why Does Waiting Cost More Than The Missed Payments?
Money invested earlier has the most years to earn returns on its returns.
In the example, skipping S$30,000 of payments costs about S$155,761 by the goal.
How Much More Would I Need To Invest To Catch Up?
In the example, starting 5 years later needs about S$725 a month instead of S$500 to reach the same total by the goal, at the same assumed return.
Should I Invest Before Having An Emergency Fund?
Keep an emergency fund and pay off expensive debt first.
The calculator only shows the effect of timing, assuming steady returns.
Try Cost Of Waiting Calculator →Get The Checklist (Free For Members)
Before You Start Investing Checklist. The checks to make before your first trade, from safety cushion to costs, scams and a yearly review.
Get The ChecklistFree account. No password needed.
Save Guides Free
Keep This Guide For Your Next Money Decision.
Build your own reading list and pick up where you left off with a free WealthMastery account.
Free account · Tools stay free without an account.
Sources & Assumptions
Sources checked 12 October 2026. These are examples only. Check the stated assumptions and limits before you use a result.
General information and estimates, not advice. Assumes a steady return with no fees, tax or inflation. Checked 4 October 2026.