Quick Answer
Compare how each rate works and how long you commit, not just the first rate. Reviewed on 13 October 2026, DBS’s 2.08% fixed rate and 1.78% CPF-OA-pegged rate both hold for three years. Then one moves to 3M SORA plus 1% and the other to 2.20%, then 2.40%. These are dated published-rate examples, not personal offers.
The Useful Number: DBS’s 2.08% fixed rate and its 1.78% rate pegged to the CPF-OA rate both hold for three years, then change in different ways.
What Did DBS Publish On The Review Date?
Reviewed 13 October 2026. DBS publishes an HDB package fixed at 2.08% for three years, then 3M SORA plus 1%. (SORA, the Singapore Overnight Rate Average, is a benchmark interest rate.) The minimum loan is S$200,000.
DBS also publishes a package pegged below the CPF Ordinary Account (OA) rate of 2.50%: 1.78% for years one to three, the lock-in, then 2.20% for years four and five and 2.40% after that. The minimum loan is S$100,000. These are published examples, not personal offers.
Both DBS packages are in our comparison. Quote-only packages from other banks are listed but not ranked. We do not cover the whole market.
- Three-Year Fixed Package
- CPF-OA-Pegged Package
- Years 1 To 3: 2.08%
- Years 1 To 3: 1.78%
- From Year 4: 3M SORA + 1%
- Years 4 And 5, Then From Year 6: 2.20%, Then 2.40%
Data as of . Source: DBS — HDB Home Loans.
Is A Rate Comparison The Same As Total Cost?
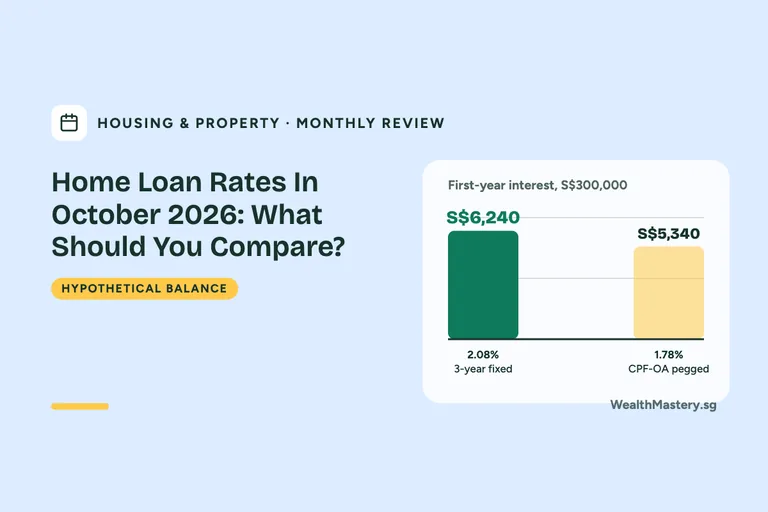
Take a hypothetical S$300,000 balance held flat for a year. At 2.08%, that is S$6,240 interest; at 1.78%, S$5,340. That simple S$900 gap holds for each lock-in year. A real loan shrinks as you repay it, so these are not the comparison calculator’s amortised costs.
From year four, the fixed package follows 3M SORA, which can rise or fall, while the pegged one steps up to 2.20%. The comparison’s floating-rate case does not predict rates.
What Happens After The Lock-In?
A three-year rate is not fixed for the whole loan. Get the full Letter of Offer and compare lock-in terms, conversion rights, fees and rebate clawbacks.
A lower headline rate does not mean you qualify for the loan. Check age, valuation, cash needs and existing debt separately with the borrowing-limit guide.
Why Ask For A Fresh Written Quote?
Ask each bank to quote the same loan amount, tenure and holding period. Confirm benchmark dates and the full cost of switching. Published packages may change or close. This static October edition reserves no rate.
Quick Check
Three statements from this guide. Tap True or False to check what you have read. Nothing is saved.
Card 1 Of 3
DBS’s 1.78% CPF-OA-pegged rate is fixed for the whole loan.
Why?
DBS’s CPF-OA-pegged package moves to 2.20% in years four and five, then 2.40%. Check the full schedule before comparing.
Card 2 Of 3
On a hypothetical S$300,000 balance held flat for a year, 2.08% and 1.78% differ by S$900.
Why?
A real loan shrinks as you repay it, so use the comparison for amortised costs on your own balance and tenure.
Card 3 Of 3
A lower headline rate means you qualify for the loan.
Why?
Check age, valuation, cash needs and existing debt separately, for example with the borrowing-limit guide.
Your Score
Review The Comparison
Check each record’s date, the eligibility rules and provider terms before you act.
Compare Home Loans →Frequently Asked Questions
Is A Three-Year Rate Fixed For The Whole Loan?
No.
Both reviewed DBS packages hold their first rate for three years only. The fixed package then moves to 3M SORA plus 1%. The CPF-OA-pegged package moves to 2.20% in years four and five, then 2.40%. Compare the whole commitment, not just the first years.
What Happens After A Fixed-Rate Period Ends?
DBS’s three-year fixed package moves to 3M SORA plus 1% after year three.
Get the full Letter of Offer. Compare lock-in terms, conversion rights, fees and rebate clawbacks, not just the first period.
How Much Difference Does The Rate Gap Make On A S$300,000 Loan?
On a hypothetical S$300,000 balance held flat for a year, 2.08% means S$6,240 interest and 1.78% means S$5,340.
That is a simple S$900 difference for each lock-in year. A real loan shrinks as you repay it, so use the comparison calculator for amortised costs.
How Should I Request Home Loan Quotes?
Ask each bank using the same loan amount, tenure and how long you plan to keep the loan.
Confirm benchmark dates and the full cost of switching. Published packages may change or close. This static October edition does not update itself and does not reserve a rate for you.
Save Guides Free
Keep This Guide For Your Next Money Decision.
Build your own reading list and pick up where you left off with a free WealthMastery account.
Free account · Tools stay free without an account.
Sources & Assumptions
Editorial review: 14 October 2026. Rates checked on 13 October 2026. This is a dated snapshot, not live rates. Each example says whether it is hypothetical or based on a source.
A snapshot of published rates checked on the review date, not loan approval. The flat-balance sums are examples, not a forecast of amortised loan costs.