Quick Answer
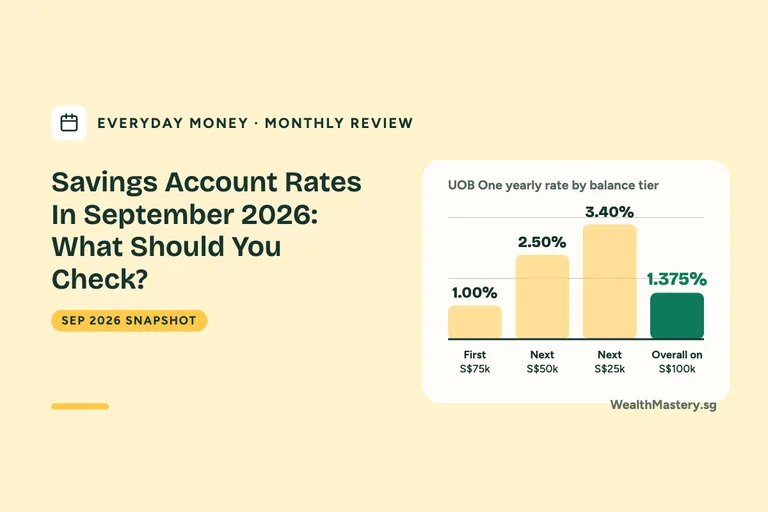
Check the tiers and qualifying conditions. Do not apply the highest advertised rate to every dollar. On the reviewed UOB One salary-and-spend tiers, S$100,000 earns S$1,375 in annualised interest under the stated assumptions. That is an effective 1.375%, not 3.4% on the whole balance. This 11 September 2026 snapshot is not a live rate feed.
The Useful Number: On the reviewed UOB One salary-and-spend tiers, S$100,000 earns S$1,375 in annualised (yearly) interest under the stated assumptions. That is not 3.4% on the whole balance.
What Does This Edition Cover?
Reviewed 11 September 2026. We model UOB One, the standard OCBC 360 schedules and the full DBS Multiplier SGD rate table, including its recognised income and category routes, balance caps, youth route and SGFinDex option. Enter only amounts DBS recognises; we do not check insurance and investment eligibility or qualifying periods. OCBC insurance and investment bonuses and temporary boosts are left out.
This limited snapshot does not show the best savings account or promise a rate is still available.
How Much Does A Tiered S$100,000 Balance Earn?
UOB’s reviewed schedule pays 1% on the first S$75,000 and 2.5% on the next S$50,000 if you meet the card-spend and salary conditions. At S$100,000 that is S$750 plus S$625 on the next S$25,000: S$1,375 a year, or 1.375% overall.
This assumes you qualify every month with a steady balance, before fees and exact rounding.
- First S$75,000 At 1%: S$750
- Next S$25,000 At 2.5%: S$625
- Yearly Interest (1.375% Overall): S$1,375
- If 3.4% Applied To All: S$3,400
Data as of . Source: UOB — One Account.
Which Conditions Can You Keep Up?
Enter your own balance, salary, spending and savings activity in the comparison. A salary transfer must use a method the bank accepts; moving money in yourself does not automatically count. Do not spend more or buy a product just for a deposit bonus.
Compare banks as alternatives: the same salary and spending cannot earn every bank’s bonus at once.
What Should You Recheck Before Moving Money?
Read the official terms and fee schedule, including minimum balances and qualifying periods. Rates can change; an October edition will replace this one. Future reviews must check every affected tier and leave incomplete schedules unranked.
Review The Comparison
Check each record’s date, the eligibility rules and provider terms before you act.
Compare Savings Accounts →Frequently Asked Questions
How Is Interest Calculated On A Tiered Savings Account?
Each tier earns its own rate.
In the reviewed UOB One schedule, the first S$75,000 earns 1% (S$750 a year). The next S$25,000 falls in the 2.5% tier on the next S$50,000 and earns S$625. You must meet the card-spend and salary conditions. The example assumes you qualify every month with a steady balance, before fees and exact rounding.
Which Accounts Does The September 2026 Edition Cover?
It models UOB One, the standard OCBC 360 schedules and the full DBS Multiplier SGD rate table.
OCBC insurance and investment bonuses and temporary boosts are left out. It is a limited snapshot and does not show the best savings account in Singapore.
Can One Salary Earn Bonus Interest At Several Banks?
The guide treats banks as alternatives.
The same salary and card spending cannot simply earn every bank’s example bonus at once. A salary transfer must also use a method the bank accepts. Moving money in yourself does not automatically count.
Are These Savings Rates Still Available?
This edition was reviewed on 11 September 2026 and does not update itself.
It does not promise a rate is still available after the review date. Rates can change while your account is open. Read the official terms and fee schedule before moving money.
Sources & Assumptions
Editorial review: 11 September 2026. This is a dated snapshot, not live rates. Each example says whether it is hypothetical or based on a source.
A dated review of standard rates with limited coverage. Yearly examples are not guaranteed future interest. They leave out fees and exact bank rounding.